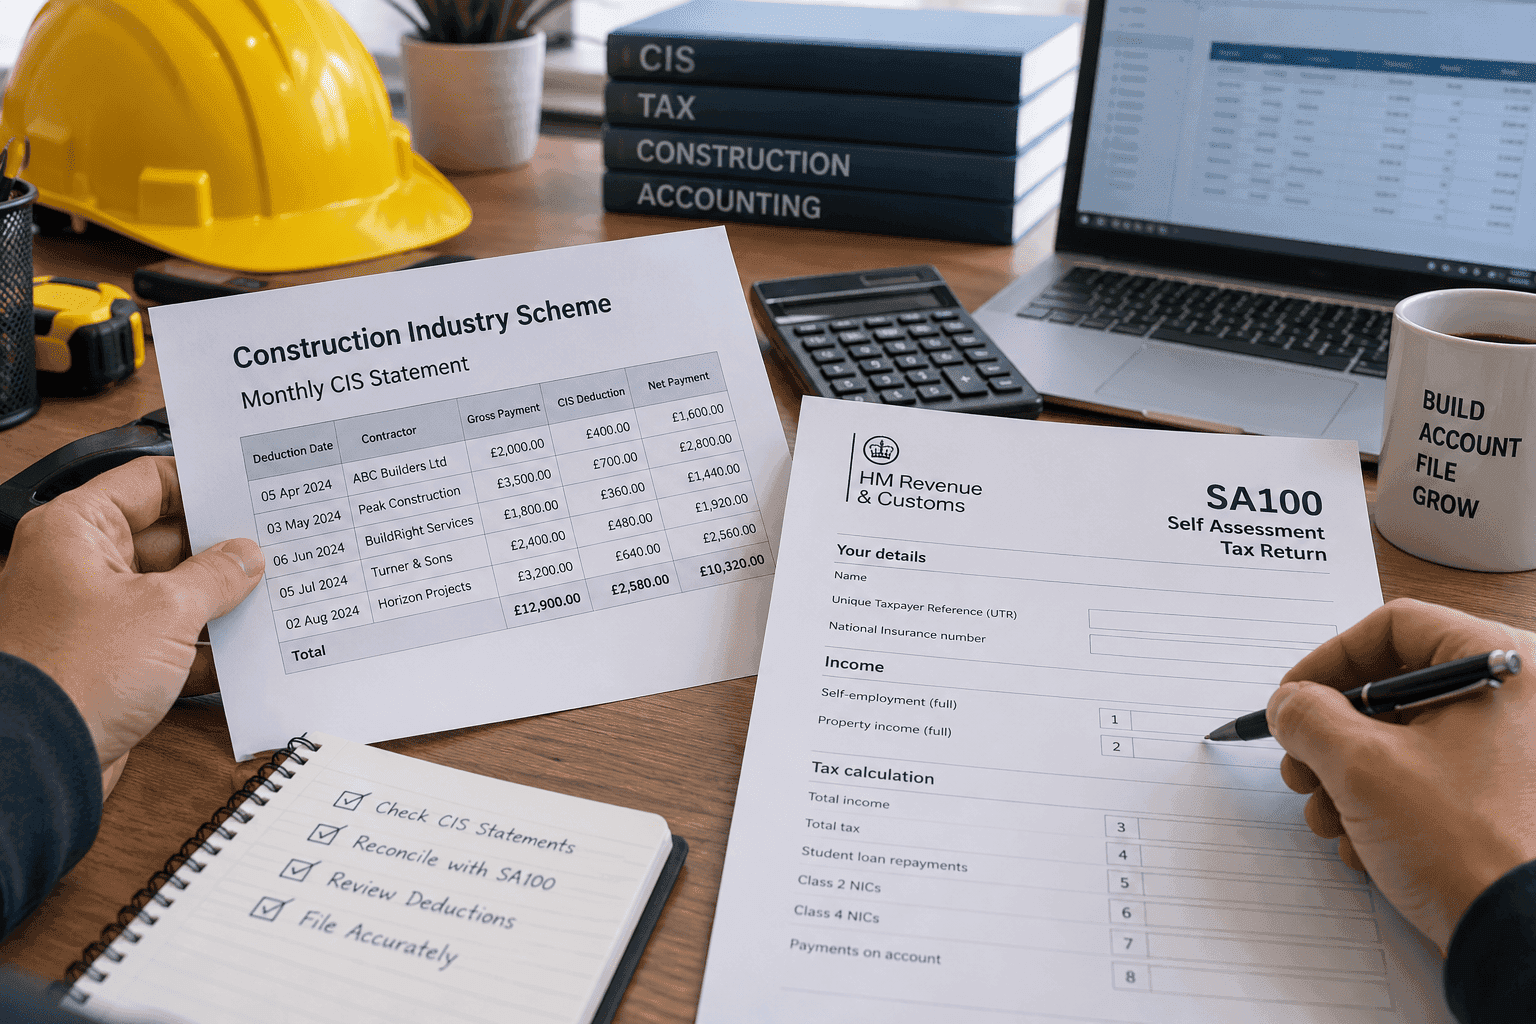
Every self-assessment season, the same file turns up on a reviewer’s desk. A CIS subcontractor, turnover somewhere around £60,000, a folder of deduction statements, a bank feed, and a refund that looked straightforward until somebody added it up. The statements say £9,400 was suffered. The ledger says £7,850. Nobody can explain the difference; the client is asking when the money lands, and the return is now sitting in the “queries” pile behind forty others.
That gap is almost never fraud and almost never HMRC’s error. It is a reconciliation problem, and it has four or five usual causes that repeat across every contractor portfolio we work on.
We prepare a high volume of CIS and self-assessment work for UK practices, which means we see the same breaks over and over. This piece follows the money from the contractor’s deduction statement, through the subcontractor’s ledger, into the SA100, and out the other side as an HMRC repayment. It names what usually goes wrong, what evidence HMRC asks for when figures do not agree, and what actually shortens the wait for a refund.
How CIS deductions reach the return
Before you can fix a break, it helps to be precise about the chain, because the deduction changes character three times on its way to the return.
A contractor verifies the subcontractor with HMRC and applies the resulting rate: 0% where the subcontractor holds gross payment status, 20% where they are registered and verified, 30% where they are not. The deduction is applied to the labour element of the payment only. The contractor then reports the payment on the monthly CIS300 return by the 19th, pays the deduction over to HMRC, and issues a payment and deduction statement to the subcontractor within 14 days of the end of the tax month.
At that point, the money has already left the subcontractor’s hands. What matters for the return is this: the deduction is tax paid on account. It is not an expense, and it does not reduce turnover. The subcontractor’s income is the gross figure before deduction. The deduction is a credit sitting against the eventual liability.
For a sole trader or partner, that credit is claimed through self assessment. The total CIS suffered goes in the CIS deductions box on the self-employment pages, feeds through to the SA100 calculation, and is set against the income tax and Class 4 National Insurance due for the year. Where the deductions exceed the liability, HMRC repays the difference. Because 20% is applied to gross labour with no regard to the personal allowance or business expenses, most subcontractors overpay during the year, which is why the CIS tax return is a refund conversation rather than a payment one.
For a limited company subcontractor, none of this happens on the SA100. Deductions suffered are offset through the Employer Payment Summary against the company’s PAYE, National Insurance, student loan and CIS liabilities, with any excess reclaimed after the tax year end. We still see director’s personal returns claiming the company’s CIS credits, usually where the same person prepared both. It is one of the faster ways to trigger an HMRC repayment check, and it is entirely avoidable if the payroll and RTI side is handled alongside the return rather than separately.
The contractor-side mechanics – verification, CIS300 submissions, statements, control account reconciliation – sit in our CIS tax return services. What follows is the subcontractor side, where the refund actually lands.
The four common reconciliation breaks
1. Turnover recorded net of the deduction
This is the most frequent single cause, and it is a bookkeeping problem rather than a tax one.
The bank feed shows £4,000 landing from a contractor. The invoice was £5,000 of labour, with £1,000 deducted. If the bookkeeping is driven off the bank feed alone – which it very often is on the simpler software tiers – turnover is recorded as £4,000. The accounts are then understated by exactly the CIS suffered, while the return claims a £1,000 credit that the declared income does not support.
The check is arithmetic. Gross turnover should equal net cash received, plus CIS suffered, plus any retentions held, plus VAT where the reverse charge does not apply. If those do not tie, the books are net and need grossing up before anything is filed. This matters more now that the cash basis is the default for sole traders: cash basis means recording income when received, but it is still the gross amount received-and-deducted, not the figure that hit the bank.
Good bookkeeping services for contractors catch this monthly, when the statement arrives and the memory is fresh. Catching it in January means rebuilding twelve months of postings against a folder of PDFs.
2. Timing and cut-off
CIS is credited by date of payment. Accounts prepared on an accruals basis are driven by invoice date. Those two will not agree at the year-end, and the mismatch clusters in exactly the place it does the most damage – March and April.
A February invoice paid on 12 April sits in the 2026/27 CIS record but in 2025/26 turnover if the books are on accruals. A 31 March year-end against a tax month running 6 April to 5 May produces the same effect. Retentions are the long-tail version: work invoiced two years ago, retention released now, deduction taken now, and nobody expects a CIS credit against income that was recognised in an earlier period.
The fix is a CIS schedule ordered by payment date, reconciled to the tax months, with a clearly identified bridge to the accounting period. Not an elegant piece of work, but it is the schedule that answers HMRC’s first question if the repayment is queried.
3. Missing, duplicated, or misallocated statements
Contractors are required to issue statements within 14 days of the tax month end. Plenty do not, particularly smaller contractors and those who have fallen behind on their own CIS300 filings. Where a contractor never filed, HMRC’s record shows no deduction for that subcontractor at all, and the claim will not match.
The mirror problem is duplication. Some contractors issue a statement per payment and a monthly summary covering the same payments. Both get scanned into the client folder, both get keyed, and the claim is overstated by a whole month.
Then there is entity mismatch. A subcontractor who incorporates mid-year but is still verified and paid under their personal UTR ends up with deductions credited to the wrong record. The individual claims on the SA100 what the company should be offsetting through the EPS, or the reverse. Verify the UTR on each statement against the entity you are filing for, every year, not just at onboarding.
4. The deduction was applied to the wrong base
Contractors over-deduct. They apply 20% to the full invoice including materials, include VAT in the deduction base, or deduct on plant hire that should have been excluded.
This one is worth being clear about, because the instinct is to correct it on the return. You cannot. The tax return claims the tax that was actually deducted and evidenced, not the tax that should have been deducted. If a contractor over-deducted, the correction route runs through the contractor: they amend the relevant CIS300 and reissue the statement. Until that happens, the statement is the claim. Where the contractor will not cooperate, and the sums are material, that becomes a client conversation about evidence and timing, not a box adjustment.
Materials, VAT, and what is actually deductible
The deduction applies to labour. What can be excluded from the deduction base is narrower than most clients assume, and wider than most contractors apply in practice.
Excluded from the deduction base: the direct cost of materials the subcontractor paid for, consumable stores, plant hire from a third party, fuel other than fuel for travelling, manufacturing or prefabrication costs, and the CITB levy. Excluded at cost, which is the part that gets missed. A subcontractor who buys £2,000 of materials and bills them at £2,400 can only exclude the £2,000 actually paid. The £400 mark-up falls into the deduction base, and the contractor is expected to satisfy themselves that a materials figure is genuine rather than simply accepting whatever is written on the invoice.
VAT never forms part of the deduction base. Where the domestic reverse charge applies — both parties VAT registered, the supply within CIS, the customer not an end user — the subcontractor charges no VAT at all, and the contractor accounts for it. The CIS deduction still applies to the labour element underneath. Getting the reverse charge wrong does not change the CIS position, but it does mean two sets of figures to unpick at once, which is why we handle the DRC treatment and the VAT returns on the same file rather than in isolation.
On the return itself, watch the double-relief trap. Materials are claimed as a business expense in the accounts. They are also excluded from the CIS deduction base. Both are correct, and both are meant to happen. What is not correct is treating a materials-inclusive invoice as pure labour for the credit while also expensing the materials. That inflates the claim and the expense ratio at the same time, which is a combination HMRC’s systems are well tuned to notice.
The refund itself is usually built from ordinary allowable expenses rather than anything clever: tools and equipment, protective clothing, van running costs, site-to-site travel, public liability insurance, phone, and use of home where it is genuine. Travel is the one that needs discipline. Site-to-site is allowable; commuting to a single long-running site that has become a permanent workplace is not, and a subcontractor who spent eleven months on one development has a weaker mileage claim than the spreadsheet suggests. Practices offering construction tax services earn their fee by having that conversation in November, not in the response to an HMRC letter in June.
The evidence HMRC asks for when figures do not agree
Where a repayment claim does not match HMRC’s record, the file needs to stand on its own. The pack we would want to be holding before filing:
- A payment and deduction statement for every payment claimed, showing the contractor’s name and employer reference, the gross payment, the direct cost of materials, and the amount deducted.
- A CIS schedule listing each statement by payment date, reconciled to both the ledger and the bank, with the monthly and annual totals agreeing to the figure going on the return.
- Bank statements evidencing net receipts, which is what lets you demonstrate gross income where a statement is missing.
- Sales invoices or applications for payment, particularly where labour and materials are separated.
- Materials invoices supporting the amounts excluded from the deduction base.
- A retention schedule, showing what is held, by whom, and when it was released.
- Mileage and expense records in contemporaneous form. Reconstructed mileage logs are visibly reconstructed.
Where statements genuinely cannot be obtained, HMRC will consider other evidence, but the claim moves from routine to reviewed. Bank statements plus invoices plus a documented written request to the contractor is a defensible position. An estimate is not. Records should be kept for at least five years after the 31 January filing deadline for the year in question.
Firms running larger contractor portfolios usually find this is the point where the arithmetic outgrows the capacity. Assembling and tying out that pack for one client is a morning’s work. Doing it for sixty, in December, while the rest of the self assessment book is also live, is why contractor accounting services get outsourced in the first place.
Speeding up the repayment
Refund timing is the thing clients actually judge you on, and most of what determines it is decided before the return is filed.
File early. A 2025/26 return filed in May sits in a far shorter queue than the same return filed on 29 January 2027. Subcontractor returns are among the easiest to prepare early, because the income record is monthly and closed by 5 April. The practices that get refunds out in six weeks are the ones that start CIS clients in April, not the ones that work faster in January.
Get the repayment details right on the return. Sort code, account number, and the account name as the bank holds it. A mismatch stops the payment and produces a letter rather than a transfer. Where the repayment is being directed to the firm as nominee, expect additional checking, and set client expectations accordingly.
Check the client’s HMRC record before filing, not after. If the deductions on your schedule and the deductions HMRC holds do not match, you want to know while you can still chase the contractor.
Deal with payments on account. A refund can be quietly consumed by a payment on account falling due on the same date, and the client experiences that as “my refund never arrived”. Where CIS deductions reliably cover the liability, a claim to reduce payments on account is often the right call. Make it deliberately and document the basis.
Expect a check on certain profiles. First returns under a new UTR, unusually high expense ratios, a large refund against modest turnover, changed bank details, or figures that do not agree with contractor submissions. None of these are problems on their own. All of them are faster to clear if the evidence pack already exists.
For company subcontractors, the EPS discipline is the whole game. Deductions suffered can only be offset in-year through the EPS. A company that never submits one accumulates a credit it cannot use and then has to claim it back after the year-end, which is slower and more heavily checked. Monthly EPS submissions, reconciled to statements received, are the difference between cash flow and a claim form.
Preparation capacity is the other half of this. Our self assessment tax return services run on a five working day turnaround through January, which is what makes early filing a portfolio-wide policy rather than an aspiration for the organised clients.
What changes now MTD for Income Tax is live
The 2025/26 return, due 31 January 2027, is the last conventional one for a sizeable slice of the CIS client base.
Making Tax Digital for Income Tax has applied since 6 April 2026 to sole traders and landlords with qualifying income above £50,000. For subcontractors, qualifying income is measured on gross income before expenses and before CIS deductions, so a subcontractor whose bank receipts look like £44,000 can comfortably be inside the threshold. The £30,000 threshold follows in April 2027 and £20,000 in April 2028, which will pull in most of the remaining portfolio.
Three practical consequences for contractor and subcontractor files:
The net-turnover problem now bites four times a year. Under self-assessment, books recorded net of CIS were wrong once, at the year-end, and could be fixed before filing. Under MTD, the same error is submitted in a quarterly update on 7 August, 7 November, 7 February and 7 May. The gross-up has to be built into the monthly routine.
CIS deductions are reconciled at the final declaration, not in the quarters. HMRC’s calculation draws on the CIS figures contractors have submitted. The refund still crystallises at the year end, and for 2026/27 the final declaration is due by 31 January 2028.
There is a route when HMRC’s CIS figure is wrong. Where the client disagrees with the deduction total HMRC holds, a corrected figure can be submitted after the fourth quarterly update and before the annual return. That is a genuinely useful mechanism, and it depends entirely on holding a reconciled CIS schedule with the statements behind it. The evidence discipline described above stops being good practice and becomes the mechanism.
HMRC is not issuing penalty points for late quarterly updates during 2026/27. Late final declarations and late payments are penalised as normal. For accountants for construction industry clients, the sensible read is that the grace period is for the software and the habit, not for the underlying records.
Frequently asked questions
Can a subcontractor claim CIS deductions without the statements?
They can file, but the claim moves into a checked queue. HMRC will consider bank statements, invoices and evidence that the statements were requested. Estimating is not a safe position, and it is worth chasing the contractor before filing rather than after a query lands.
Why does the refund not equal the CIS suffered?
Because the deductions are set against the whole liability first. Income tax and Class 4 National Insurance on profits come out, along with tax on any other income, and only the excess is repaid. A subcontractor with a profitable year and modest expenses may owe more than the deductions cover.
Can a limited company subcontractor reclaim CIS through self assessment?
No. The company offsets deductions suffered through the Employer Payment Summary against its PAYE and CIS liabilities, and claims any excess after the year end. The director’s personal return is the wrong place for it, and putting it there reliably delays both.
Does gross payment status remove the self assessment obligation?
No. It removes the deduction at source. The income is still declared and the tax still paid, just in one payment rather than through the year. Since April 2024, VAT compliance forms part of the gross payment status test, and HMRC can cancel the status without notice in serious cases, so a run of late VAT returns can cost a client the cash flow position they had built a business around.
When should a practice start its CIS returns for the year?
April, for anything with a refund attached. The income record closes on 5 April, and there is no advantage in waiting. Refunds filed in the spring clear materially faster than the same work filed in January.
Getting the CIS book off the critical path
Most of what delays a CIS refund is decided long before January. Net-recorded turnover, statements nobody chased, a materials figure taken on trust, a schedule that was never reconciled to the tax months. By the time the return is being prepared, those are archaeology, and archaeology is slow.
We work as the back office for UK practices carrying contractor portfolios: monthly construction bookkeeping services with the CIS gross-up built in, CIS300 preparation and deduction statements before every 19th, and self assessment returns delivered reviewer-ready in five working days through peak. Your reviewer signs off, your client gets a refund date instead of an apology.
If you want to test it rather than take our word for it, send us one real CIS file — ideally the one with the folder of mismatched statements. We will reconcile it, prepare the return, and hand back a pack your reviewer can sign.
Start a free trial or talk to our construction team.
Related reading: Construction accounting outsourcing for UK practices | CIS tax return services | Outsourced self assessment
This article is general guidance for UK accountancy practices and is not a substitute for advice on a specific client file. CIS and MTD for Income Tax rules are subject to change; figures and thresholds are those applying for the 2025/26 and 2026/27 tax years as at publication.
Need help outsourcing this to a specialist team?
We handle bookkeeping, VAT, payroll, and year end accounts for UK accounting firms from India. Start with a free trial. No commitment required.