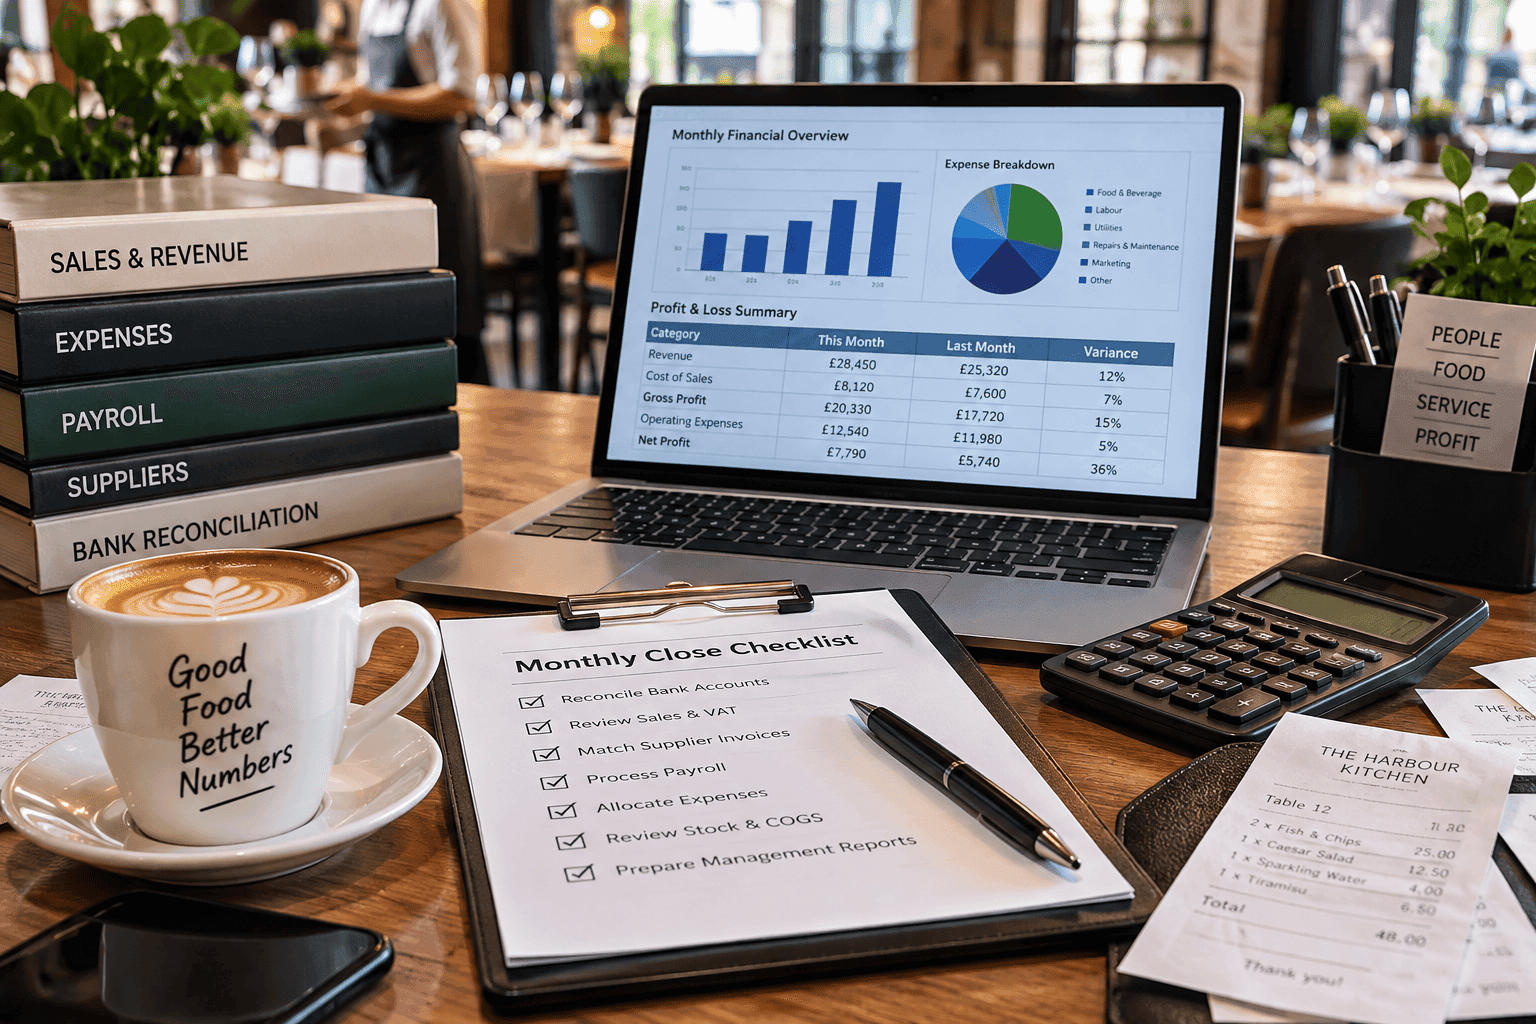
There is a particular kind of phone call that lands in a practice around the second week of January. A restaurant client wants to know why December looked so strong on the bank statement and so ordinary in the accounts. Or why gross profit has moved four points with no obvious change in the menu. Or why the VAT bill is bigger than the bookkeeper said it would be.
Nine times out of ten, the answer has nothing to do with December. It goes back to a close routine that was never quite tight enough, running in a month where volume was low enough to hide it. Come peak trading, the same routine carries four times the transactions, and the cracks stop being cosmetic.
October is the right month to fix this. Whatever your clients’ peak looks like — Christmas parties, a hotel’s winter half-term, New Year’s Eve, a January conference season — the close routine you are running now is the one that has to survive it. This article sets out what a complete monthly close looks like on a hospitality file: the order things happen in, the journals that carry the sector’s quirks, and the reconciliations that have to clear before anybody signs off a number.
We have been delivering hospitality accounting services to UK practices for over a decade, across restaurants, pubs, hotels, bars and café groups. The routine below is the one our team works to on live files. It is deliberately specific, because in this sector the general advice (“reconcile the bank, post the journals”) is exactly where files go wrong.
Why hospitality months close differently
Most SME files close on a rhythm of sales invoices out and purchase invoices in. Hospitality has neither in any meaningful volume. What it has instead is:
Daily takings, not invoices. A single site can produce thousands of transactions a day across cash, card, delivery aggregators, room charges, gift cards and house accounts. None of it arrives as a sales invoice. It arrives as an EPOS report that has to be turned into a journal.
Stock that genuinely moves the numbers. In most sectors, a stock figure is a year-end tidy-up. In hospitality, the stock adjustment is the difference between a gross profit figure the operator can act on and one that is simply wrong. A two-point GP swing on a £1.2m site is £24,000 — and it hides comfortably in a file where stock is only counted twice a year.
A payroll that runs on a different calendar to everything else. Weekly rotas, constant starters and leavers, age-banded wage rates, and tips that legally sit outside contractual pay. The payroll journal on a hospitality file is rarely a single monthly posting.
A trading period that may not be a calendar month. Plenty of operators run a 4-4-5 calendar, or thirteen four-week periods, precisely so that period-on-period comparisons hold the same number of weekends. That is good management discipline and a genuine nuisance for bookkeeping, because the trading period no longer lines up with the VAT quarter, the payroll month, the rent quarter or the utility billing cycle. Somebody has to reconcile the trading period back to the calendar month before anything gets filed.
A short shelf life on the numbers. An operator deciding whether to change a menu, cut a shift or push a promotion needs last period’s figures while they can still act on them. Management accounts delivered six weeks after period end are a compliance artefact, not a decision tool.
Put together, that is why bookkeeping for hospitality is a process question before it is a technical one. The technical treatments are not exotic. The discipline of doing them in the right order, every period, is what separates a clean file from a painful one.
Step one: daily sales into the ledger
The single biggest source of error we see on inherited hospitality files is takings posted from the bank statement. It is quick, it looks reconciled, and it is wrong. Bank deposits are what is left after card fees, aggregator commission, refunds, chargebacks, and cash retained in the safe. Post those as sales, and you have understated turnover, lost the VAT split, and destroyed any chance of a meaningful GP figure.
The correct mechanism is a daily sales journal, built from the EPOS Z report, posting gross and letting the deductions land where they belong.
A well-structured daily sales journal carries:
Credits (the income and liability side)
- Sales by revenue category, split by VAT rate – wet, dry, hot takeaway, cold takeaway, accommodation, room service, function income, retail
- Output VAT, separated by rate, not by a single blended calculation
- Tips and service charge collected – a liability, not revenue, and never blended into sales
- Deposits taken for future bookings – deferred income, with the VAT position handled separately (more on this below)
- Gift cards and vouchers sold – a liability until redeemed
Debits (the settlement side)
- Cash taken
- Card takings, posted gross to a card clearing account
- Aggregator sales (Deliveroo, Uber Eats, Just Eat), posted gross to an aggregator clearing account so commission and marketing fees show as cost rather than disappearing into net revenue
- House accounts and room charges, posted to the relevant debtor
- Discounts, comps, staff meals and wastage, posted to their own nominals so the operator can see what they are giving away
Two rules make this work in practice. First, post daily or weekly, never monthly in one lump — a single monthly journal makes variance investigation impossible, because you cannot isolate the day the problem occurred. Second, use clearing accounts properly. Card takings go into the clearing account on the trading date and come out when the merchant settlement hits the bank, net of fees. The fees post to a cost line. The clearing account should return to near nil within a few days. If it does not, something is missing — a settlement, a terminal, a batch, a chargeback — and you now have an early warning system instead of a year-end surprise.
Gift cards and deposits deserve their own paragraph in October specifically. A deposit taken in October for a December party is deferred income in the P&L, but receipt of the payment generally creates a VAT tax point, so the VAT falls in the period the money arrives. Retained deposits where the customer cancels are, under HMRC’s position since 2019, normally still consideration for a supply with VAT due. It is worth agreeing the treatment with the client now rather than in the January return, because on a busy function site the numbers are not small.
The mechanics of tying EPOS totals back to bank receipts sit alongside this and deserve their own treatment – we cover them in detail in our guide to EPOS reconciliation. The point for the monthly close is simple: sales enter the ledger from the EPOS, never from the bank.
Step two: purchases and supplier statements
Hospitality purchase ledgers fail in a handful of predictable ways, and all of them distort gross profit.
Delivery notes are not invoices. Kitchens sign for goods daily, and the invoice arrives later, often weekly or fortnightly, often summarised. If you post from delivery notes, you will double-count. If you only post from invoices, you will have cut-off problems. The answer is a goods received not invoiced accrual at period end, built from the delivery notes sitting in the kitchen folder that have no matching invoice yet.
Credit notes get lost. Short deliveries, rejected stock, quality credits and keg returns are agreed verbally with a driver and never chased through to a document. The supplier statement reconciliation is what catches this.
Coding drifts. Food, wet stock, packaging, cleaning chemicals, kitchen consumables and small equipment all arrive from the same three suppliers on the same invoices. If packaging and cleaning materials are coded to food purchases, food GP is understated, and nobody can work out why. Line-level coding on the main food and drink suppliers is not optional on a file where GP is the headline metric.
Rebates and retro discounts sit unrecorded. Brewery discounts, volume rebates and supplier support payments are often paid quarterly or annually and only appear when the cash lands. Where they are material and reliably measurable, they should be accrued against cost of sales in the period the purchases were made, not recognised as a windfall two quarters later.
Run a supplier statement reconciliation every period on the top suppliers by value – typically the brewery or drinks wholesaler, the main food supplier, and any linked-agreement supplier. On a multi-site operator, run it by site. Statement reconciliation is dull work, and it is the most reliable single control on a hospitality purchase ledger.
Then there are the costs that never arrive as a neat monthly invoice at all:
- Utilities. Quarterly billing and estimated meter readings mean the P&L swings for reasons unconnected with trade. Post an accrual for utilities based on a consumption profile, trued up when the actual bill lands. On seasonal sites – anywhere with a beer garden, a pool, or heavy winter heating – flat-rate accruals are worse than useless. Weight them.
- Rent, service charge and business rates. Quarter days do not respect period ends. Spread them.
- Insurance, premises licence, PRS/PPL music licensing, TV subscriptions, pest control, waste. Annual or quarterly, all of them, and all of them distort a single period if posted as paid.
Step three: stock and cost of sales
This is the step most often skipped, and it is the one the operator actually cares about.
The mechanics are simple: opening stock + purchases − closing stock = cost of sales. Everything difficult about it is operational.
Count on the same day the period ends, and count the same way every time. A count taken on the Sunday when the period ended on the Friday introduces two days of trade into the variance, and nobody will ever unpick it.
Value consistently, at cost excluding recoverable VAT. Mixed valuation methods between periods make the trend meaningless, which is the only thing the trend was for.
Post the stock adjustment as a journal in the ledger. Wet stock reports from an external stocktaker are common and useful, but we regularly pick up files where the stocktaker’s GP report is emailed to the operator each period, and the ledger never sees it. The client then has two sets of numbers that disagree, and no confidence in either. Take the stocktaker’s closing valuation, post it, and reconcile the stocktaker’s reported GP to the GP in the accounts. Where they differ, the difference is information – usually coding, sometimes the count date, occasionally something the operator needs to know about.
Split stock by category. Wet, dry, food, packaging and retail behave differently, and a blended GP figure tells an operator nothing actionable. Wet GP falling while food GP holds is a very different conversation to the reverse.
Deal with wastage, staff meals and comps explicitly. They are a cost of running the business, and they belong on their own nominals. Buried inside cost of sales, they look like theft or yield loss and send the operator chasing the wrong problem.
Step four: payroll journals
Labour is usually the largest single cost on a hospitality P&L and the one with the most moving parts in 2026.
Weekly payrolls straddling the period end. A weekly payroll almost never ends neatly on the last day of the month. The days either side have to be accrued consistently, in both directions. Where the client runs a 4-4-5 calendar, weekly payroll lines up rather better — one more reason operators use it.
The journal itself. A complete payroll journal posts gross pay by department or site, employer’s NIC, employer pension contributions, apprenticeship levy where relevant, with the credits landing in a net pay control, a PAYE/NIC control and a pension control. Each of those controls then clears against actual payments. Posting the net bank payment as a wages cost, which we still see, understates wage cost by roughly a third and leaves the PAYE liability off the balance sheet entirely.
Tronc. Tips are not the employer’s money. Under the Employment (Allocation of Tips) Act, qualifying tips must be allocated fairly and paid to workers by the end of the month following the month the customer paid them, with allocation records kept for three years. In the ledger, that means tips collected sit as a liability from the day they are taken, the Tronc distribution clears that liability, and the balance at period end should equal what is genuinely still to be paid out. A Tronc liability that only ever grows is a compliance problem, not a bookkeeping one, and it is far better found in October than in a payroll inspection. Tronc payroll runs separately from contractual pay and should never blur into it on a payslip or in the nominal ledger.
Wage rates and absence costs, 2026 edition. From 1 April 2026, the National Living Wage is £12.71 for workers aged 21 and over, £10.85 for 18 to 20-year-olds and £8.00 for 16 and 17-year-olds and apprentices, with the daily accommodation offset at £11.10 — directly relevant to hotels with live-in and seasonal staff. From 6 April 2026, Statutory Sick Pay is payable from the first day of absence, the Lower Earnings Limit is gone, and the rate is the lower of £123.25 a week or 80% of normal weekly earnings. On a workforce built around part-time and variable hours, that is a real change to the cost of short absences, and it shows up as a growing line in the payroll journal rather than as an event. Flag it in the commentary before the client notices it in the bank balance.
Holiday pay accrual for variable-hours staff. Rolled-up holiday pay is permitted for irregular hours and part-year workers where the arrangements are right, but the accrual still has to be carried where it is not paid as it accrues. It is an easy period-end adjustment to forget and a material one on a large casual workforce.
Our outsourced payroll services team runs weekly hospitality payrolls alongside Tronc as standard, and the journal comes back mapped to the client’s chart of accounts rather than as a summary PDF for somebody else to re-key.
Step five: the reconciliations that must clear
This is the part that decides whether the close is finished. Our working rule: if a control or clearing account holds a balance nobody in the room can explain, the period is not closed. Not “closed with a note”. Not closed.
On a hospitality file, the list is:
| Account | What clearing looks like |
| Bank – all accounts | Fully reconciled, including deposit accounts, savings and any site petty cash account |
| Card clearing | Near nil. Aged items mean a missing settlement, an unbanked terminal, or an unposted chargeback |
| Cash control / safe | Agrees to the counted float and safe balance; unbanked cash aged and explained |
| Aggregator control | Gross sales less commission, refunds and marketing fees ties to the remittance |
| Gift card and voucher liability | Agrees to the EPOS or provider’s outstanding balance report |
| Deposits and deferred income | Agrees to the forward bookings schedule, event by event |
| VAT control | Reconciles to the return filed, with the split-rate analysis behind it |
| PAYE/NIC control | Agrees to the HMRC business tax account statement |
| Net pay and pension controls | Clear to actual payments and to the pension provider’s schedule |
| Tronc liability | Agrees to tips collected less tips paid, within the statutory timetable |
| Stock | Agrees to the counted valuation, by category |
| Supplier control | Agrees to statements for the major suppliers |
| Intercompany / inter-site | Nets to nil across the group |
That table is, in practice, the whole of hospitality accounts reconciliation. Everything upstream exists to make these balances explainable.
One warning about VAT specifically. The split between standard-rated alcohol and adult soft drinks, standard-rated hot food eaten in or taken away, and zero-rated cold takeaway food is where hospitality returns are made or lost – and meal deals, mixed menus and event catering all need apportionment agreed in advance rather than assumed at filing. Hotels add the reduced value rule on stays running beyond 28 days. If the VAT control reconciles but the rate split behind it was never checked, the reconciliation has proved only that the arithmetic works. Our VAT services team runs the rate analysis as a separate exception check before a hospitality return goes anywhere near submission.
Step six: the close timetable
Operators need period figures while they are still useful. A five working day close is achievable on a well-run hospitality file, and this is how the days divide.
Day 1 – Sales and cash: All daily sales journals posted through to period end. EPOS totals reconciled to card settlements and banked cash. Aggregator remittances matched. Stock counts received from every site.
Day 2 – Purchases: Purchase ledger complete to period end. Goods received not invoiced accrual posted from unmatched delivery notes. Credit notes chased. Coding reviewed on the major food and drink suppliers.
Day 3 – Payroll, stock and adjustments: Payroll journals posted, including the straddle accrual and Tronc. Stock adjustment journal posted by category. Accruals and prepayments run – utilities, rent, rates, insurance, licences, marketing.
Day 4 – Reconciliations: Every account in the table above cleared and evidenced. VAT control agreed. Trial balance reviewed for anything sitting in a suspense or default nominal.
Day 5 – Reporting and review: Management pack produced and reviewed by someone who did not prepare it. P&L by site, GP by category against prior period and budget, labour as a percentage of revenue, EBITDA, and – for hotel accounting services – occupancy, ADR and RevPAR with departmental splits across rooms, food and beverage. Variance commentary written in language the operator will actually read.
Two additions worth building into the routine. First, keep a short period file each month: the stock report, the supplier statements, the payroll summary, the reconciliation evidence. Done properly, twelve of those files make the year-end job a review rather than a reconstruction, which is the single biggest lever on your year-end accounts fee recovery. Second, where the client runs a 4-4-5 or thirteen-period calendar, keep a standing bridge between trading periods and calendar months, because VAT, PAYE and Companies House do not care about the trading calendar.
Using October well: getting the file peak-ready
If you are reading this in the run-up to a client’s busiest quarter, there are five things worth doing now rather than in the middle of it.
- Test the close on a quiet month. Run the full five-day routine on October, with every reconciliation cleared. Whatever breaks will break far worse in December.
- Agree the trading calendar in writing. Period end dates, stock count dates, payroll cut-offs, and who is responsible for each. Christmas week is not the time to discover the stocktaker and the bookkeeper disagree about the period end.
- Set up deferred income and deposits properly before the deposits arrive. A schedule per event, with the VAT position agreed, is ten minutes of work in October and a day of unpicking in January.
- Check the Tronc position. Allocation policy documented, records being kept, tips paid inside the statutory timetable. Peak trading multiplies the tips volume and the exposure with it.
- Confirm capacity. Peak season is where files slip — not because anyone lacks the skill, but because the same team is doing four times the transaction volume alongside everything else in the practice.
That last point is the honest one. Most hospitality files do not go wrong through technical error. They go wrong because December’s volume arrived and the routine quietly dropped to the parts that felt most urgent, which is never the reconciliations.
Frequently asked questions
How long should a hospitality monthly close take?
Five working days from period end to a reviewed management pack is a realistic target for a well-run file, including multi-site operators. Files that habitually take three weeks usually have a cause that is identifiable and fixable: takings posted from the bank, no stock adjustment, or a purchase ledger that runs a month behind.
Should hospitality clients use a 4-4-5 calendar?
It suits operators who manage on week-on-week comparisons, because every period contains the same number of weekends and the same number of paydays. The cost is that trading periods stop aligning with VAT quarters, calendar-month payroll and statutory reporting, so a bridge between the two has to be maintained. For single-site owner-managed businesses, calendar months are usually simpler. For groups managing on covers and labour percentages, 4-4-5 generally earns its keep.
Do stock counts really need to be monthly?
For wet stock in a pub or bar, yes — that is where yield loss shows up and monthly is the minimum for it to be actionable. For food stock, monthly is strongly preferable because it is the only way GP means anything. Counting twice a year produces a cost of sales figure that is arithmetically correct over the year and useless in any individual month.
Where do tips sit in the accounts? Tips and service charge are a liability from the moment they are collected, cleared when they are distributed through the Tronc. They are not turnover, they are not the employer’s cash, and they must be allocated and paid to workers by the end of the month following the month the customer paid them, with records kept for three years.
What is the most common error you find on inherited hospitality files?
Sales posted net from bank receipts. It understates turnover, loses the VAT rate split, makes gross profit meaningless, and hides card settlement problems and chargebacks completely. Rebuilding the daily sales journals is usually the first job on a takeover file.
Can the monthly close be outsourced without losing control of the client relationship?
Yes, and it is one of the cleaner workflows to move, because it is high-volume, rules-based, and repeats identically every period. The client relationship, the review and the commentary stay with the practice. We have written more on choosing which workflows to move first in our guide to finance and accounting outsourcing, and on how practices structure the arrangement in Outsourced Accounting Services UK.
Where we fit
We work as the back office for UK accountancy practices, not as a competitor for their clients. On hospitality files, that means running the daily sales journals, the purchase ledger, the stock adjustments, the payroll and Tronc, and every reconciliation in the table above — then handing back a reviewed pack that fits your template and your review process.
Our hospitality bookkeeping services run to a five-working day close, with site-by-site detail intact and management accounts carrying the metrics operators actually manage on. The team works in Xero, QuickBooks, Sage and Zoho Books, alongside the EPOS and rota platforms feeding them.
If you have a restaurant, pub, hotel or café group where the close is slipping — or one you are about to take on before peak season — send us the messiest one. We will walk you through how we would handle it on the real file, before you commit anything.
Start a free trial on a single hospitality client, or talk to our team about accounting services for hospitality across your portfolio.
Probal Global provides outsourced bookkeeping, payroll, VAT, year-end accounts, and tax support to UK accountancy practices. GDPR-compliant, ISO 27001 aligned, NDA signed on every engagement.
Need help outsourcing this to a specialist team?
We handle bookkeeping, VAT, payroll, and year end accounts for UK accounting firms from India. Start with a free trial. No commitment required.